
Search
- Contact Us
- Claims
-
Log In
If you haven’t registered your account for online access yet, register now.
Other Products
Quick Links
thought leadership
How life insurance can change a financial strategy
New York Life | September 14, 2026
Ramon Casanova, SVP and Head of Life Insurance Solutions, explains why protection and growth belong in the same financial conversation

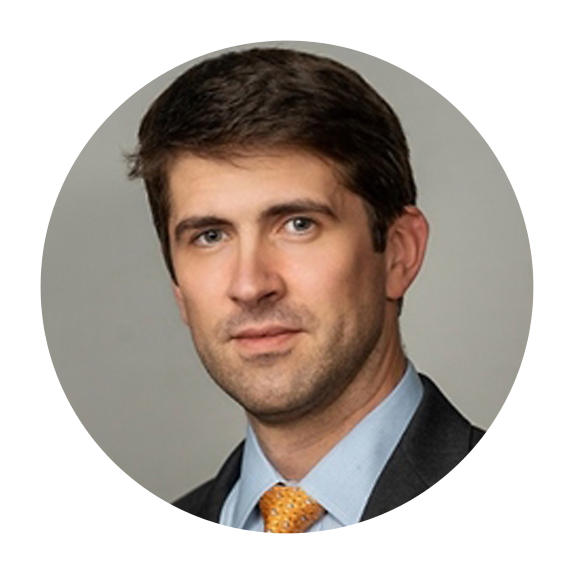
Ramon Casanova
Ramon Casanova is SVP and Head of Life Insurance Solutions at New York Life, leading the business responsible for developing life insurance solutions that help individuals and families protect the people and commitments that matter to them while adapting to changing financial needs across a lifetime.
September is Life Insurance Awareness Month. What do you think is missing from the way people commonly think about life insurance?
Life insurance is often framed around a single event: what happens financially when someone dies. That is its essential purpose, but it can lead people to underestimate how protection can change a financial strategy and the role it can play in longer-term financial planning.
Protection solutions like life insurance can create greater certainty around financial outcomes that may be difficult to address with other assets alone. That matters because most people are simultaneously trying to grow wealth, manage risk and meet commitments that may extend for decades or even generations.
What do you mean when you say life insurance can change the rest of a financial strategy?
Every financial strategy involves deciding where to take risk and where greater certainty has value. Growth assets are designed to participate in opportunity, and accepting some market risk is part of pursuing long-term growth. But there are financial outcomes people may be less willing to leave exposed to market timing or other circumstances they cannot control.
Life insurance can create more certainty around some of those outcomes. Once that foundation is established, other assets can be positioned to do different jobs. By addressing both protection and growth together in the same strategy, you can build a more complete strategy than you can by addressing them separately.
Some life insurance solutions are designed to provide both protection and growth potential, while others place greater emphasis on guarantees and stability. Different solutions can balance those objectives in different ways depending on the outcomes they are designed to support.
Life insurance is usually described as protection. Where does its role as a financial asset fit?
Permanent life insurance can have characteristics that are valuable during life as well as at death.
With whole life, cash value grows based on guarantees in the policy, which can be further enhanced through potential policy owner dividends. That cash value can provide a source of asset growth and financial flexibility that is not directly tied to market performance.
Variable life insurance takes a different approach. It allows cash value to participate in the market through investment options, creating greater growth potential along with greater variability.
Those differences are important. Life insurance is a broad product category, and different designs combine protection, guarantees, accumulation potential and flexibility in different ways. The key is understanding what each product is built to do rather than evaluating every form of life insurance through the same lens. A financial professional can play an important role in determining the best approach.
People have more financial products and investment options than ever. Why does the structure of the insurance company still matter?
Life insurance involves a very long promise. A policy issued today may still be performing its core function decades from now. Over that period, there will be recessions, market cycles, changing interest rates and events we cannot predict today. The ability of the insurer to manage through those environments matters.
New York Life is a mutual company, which means our success is tied to our policy owners rather than public shareholders. That structure supports a long-term orientation toward financial strength, product performance and the promises we make.
For products such as whole life, guarantees can extend across an entire lifetime, and dividends, while not guaranteed, can contribute to long-term value. When the promise is measured in decades, the company behind that promise should be part of the product decision.
What do you think consumers misunderstand about permanent life insurance?
One misconception is evaluating permanent life insurance by asking only whether term insurance would provide a less expensive death benefit than permanent life insurance.
Term and permanent insurance are built to do different things. Term is designed to provide protection for a defined period. Permanent insurance is designed for needs that may last a lifetime and can also include cash-value accumulation and other features that can help address a consumer’s growth needs alongside their protection needs.
Another misconception is treating permanent life insurance as though it were simply another investment. Its value comes from the combination of protection and, depending on the product, guarantees, cash value and other features that can perform different functions over time.
Any comparison should start with what the product is designed to accomplish.
How does legacy fit into that broader view?
Some financial commitments can extend beyond an individual lifetime. The question then becomes how to create greater certainty around what will be available when the next generation needs it, regardless of what markets or other assets are doing at a particular moment.
Survivorship insurance is one solution designed around that need. It covers two lives and pays a death benefit after the second insured dies, which can align coverage with when assets ultimately transfer to the next generation.
Does thinking about protection this way change when the conversation should begin?
It can, because financial responsibilities do not arrive according to a fixed timetable.
Life insurance conversations have traditionally centered on adding protection at a handful of life milestones, such as marriage, having children or buying a home. Those remain important, but financial lives have become more varied. People may be building businesses, supporting multiple generations, accumulating wealth or taking on significant financial commitments at very different points in their lives or all at the same time.
That makes protection an ongoing consideration rather than a conversation tied to a particular age or life stage. As responsibilities and financial circumstances change, the role different forms of protection can play can change with them may change, too.
Where do you see the greatest opportunity for life insurance in the years ahead?
The greatest opportunity is to broaden the way people understand the role of protection.
For a long time, financial services has tended to put growth and protection into separate conversations. Consumers do not necessarily see their financial lives that way. Our latest Wealth Watch research found that 84% of Americans believe a financial strategy should address growth and protection together.
That creates an opportunity for our industry. Our financial professionals are uniquely positioned to offer a range of solutions that recognize that people want to grow wealth, preserve flexibility and create greater certainty around the commitments that matter most to them.
Life insurance has a distinctive role because an insurer can make promises that other financial products cannot. The opportunity ahead is to make that value easier to understand and continue evolving the solutions that deliver it.
Go back to our newsroom to read more stories.